
Getting a surety bond is often a necessary step toward opening a business, securing a license, or landing a contract. But unexpected costs, confusing requirements, and misunderstandings about coverage can make the process more complicated than business owners anticipate. To uncover the biggest surprises, we surveyed 270 U.S. small business owners who purchased a surety bond in the past three years. Their experiences reveal common mistakes, missed opportunities, and lessons that can help future buyers approach the bonding process with greater confidence.
Key Takeaways
- 1 in 2 bonded owners delayed a business launch or lost a contract because of the cost or timing of getting bonded.
- 52% of bonded owners have turned down a job or decided not to bid on a contract after learning they would need to be bonded.
- One-third of bonded owners (32%) believed a surety bond protected them, not their customers.
- Only 50% of bonded owners knew they would have to repay the surety company if a claim was paid.
- 39% of bonded owners discovered after buying that their bond didn’t cover something they assumed it did.
- Nearly 2 in 5 bonded owners (38%) used an AI tool for bond guidance, and 22% of them say it got something wrong.
The Hidden Costs of Getting Bonded
For small business owners, getting bonded can be an important step toward new opportunities. Understanding the costs and requirements ahead of time can help prevent unexpected obstacles during the process.
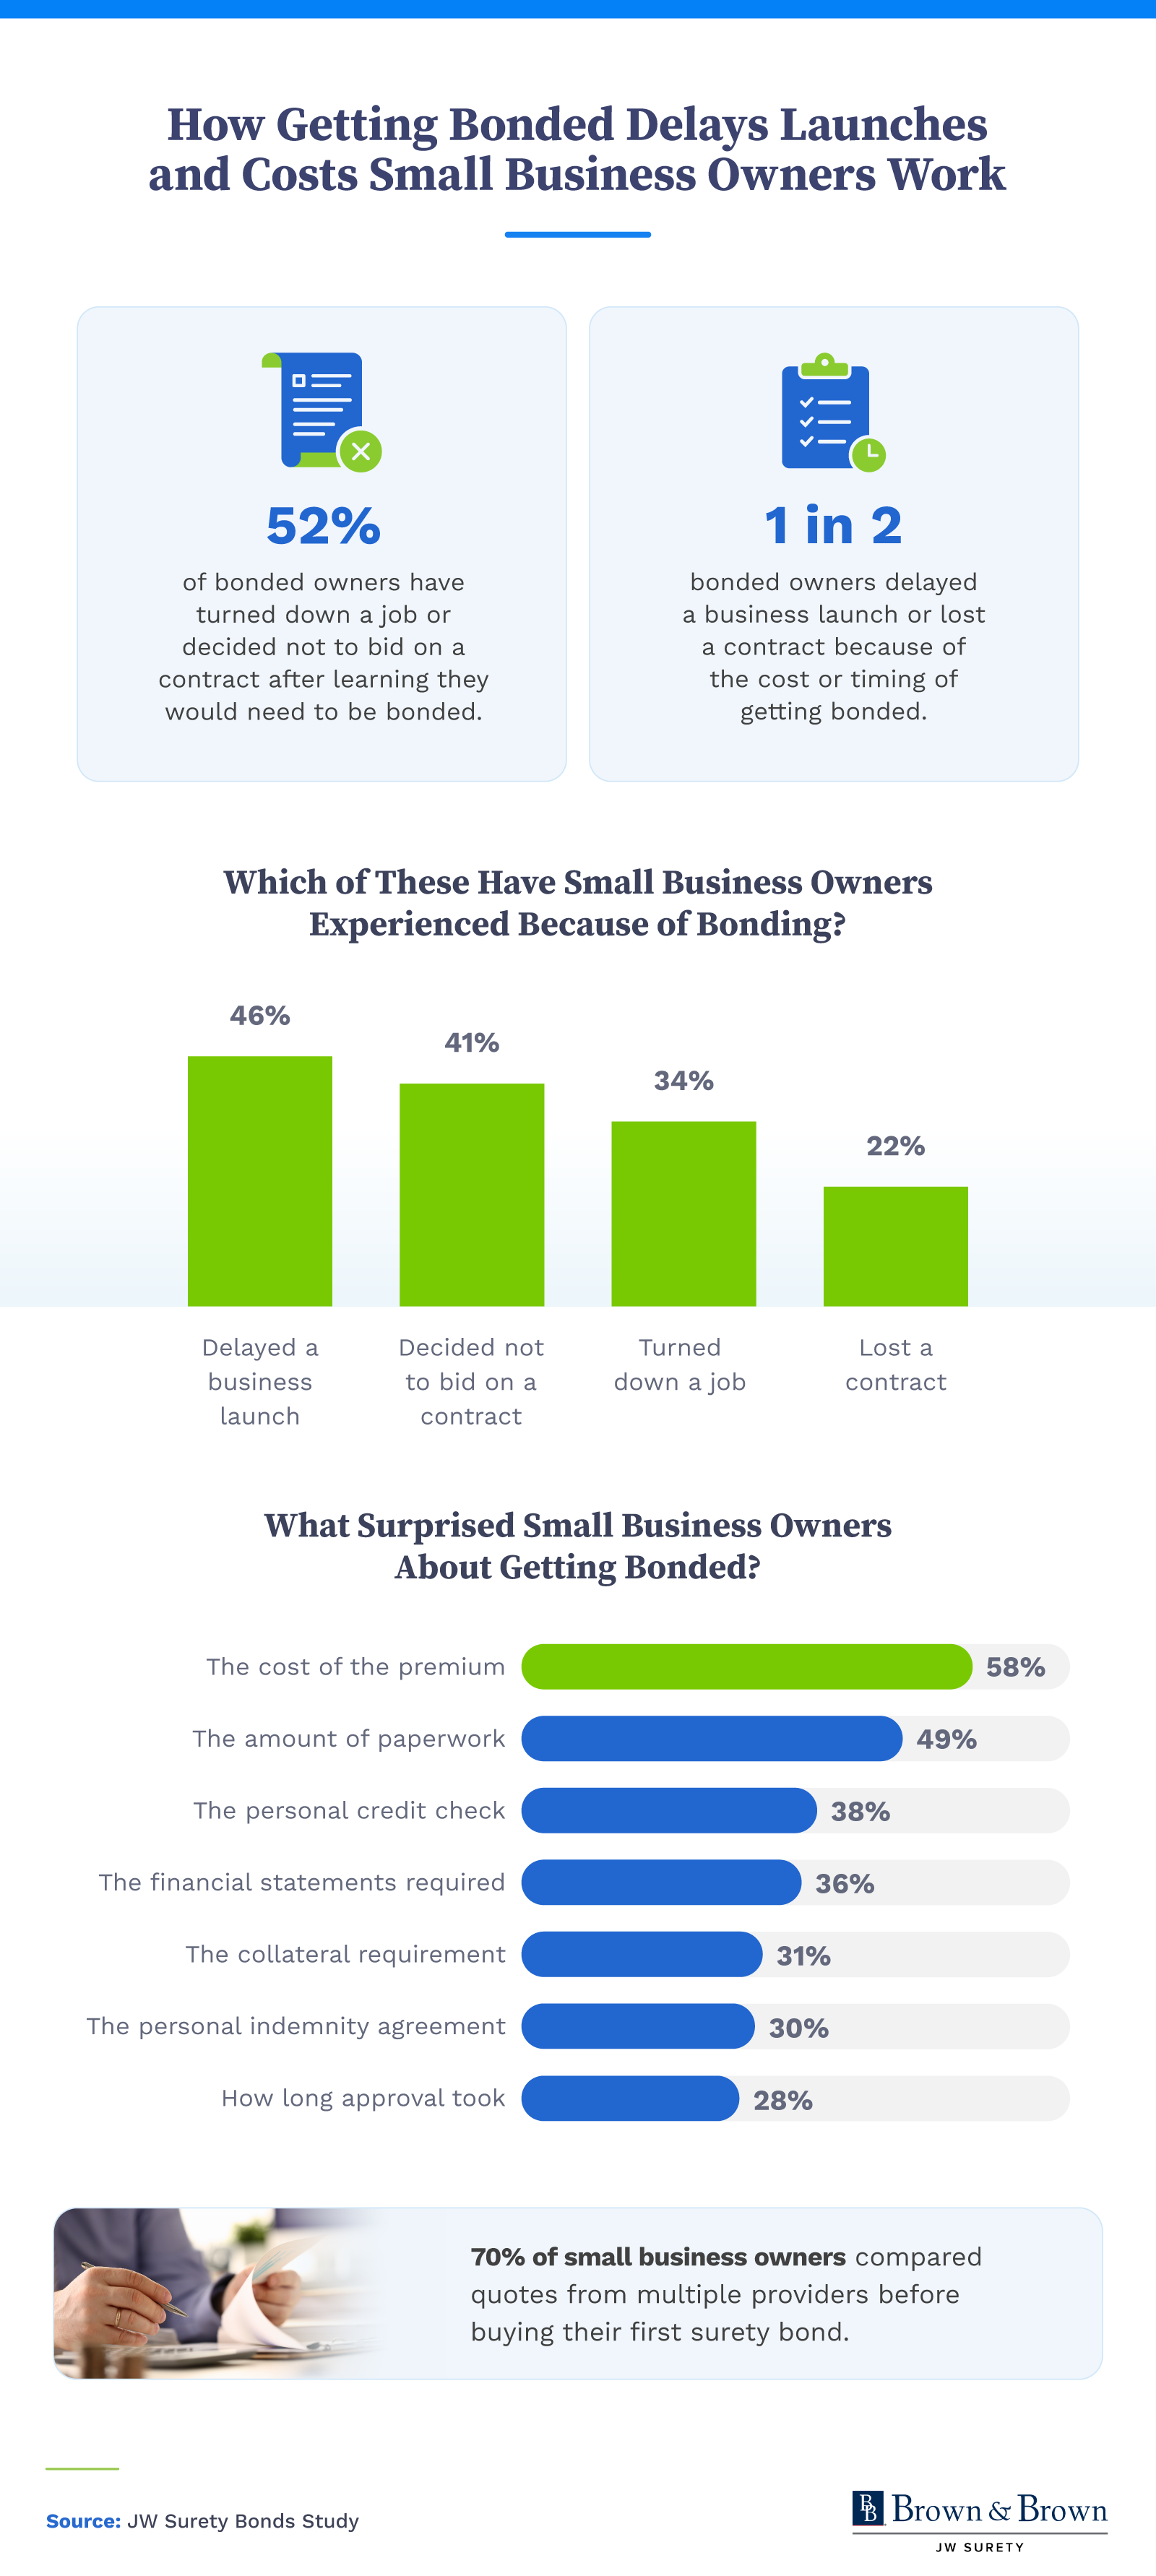
Getting bonded created unexpected challenges for many business owners. Nearly 9 in 10 (88%) were surprised by at least one part of the process, and 45% paid more for their first surety bond than they had expected. Even with 70% comparing quotes from multiple providers before purchasing, unexpected expenses remained a common experience.
The consequences went beyond higher costs. More than half (52%) of bonded owners had turned down a job or decided not to bid on a contract after learning they needed a surety bond. Additionally, 1 in 2 reported delaying a business launch or losing a contract due to the cost or timing of obtaining bonding.
These findings highlight why understanding surety bond costs and requirements early matters. Before pursuing a license or contract, business owners can benefit from researching the type of bond they need, comparing quotes, and accounting for the time required to complete the bonding process.
What Business Owners Misunderstand About Surety Bond Protection
Surety bonds play an important role in protecting customers and ensuring businesses meet certain obligations. However, understanding who receives that protection and how claims work is just as important as purchasing the bond itself.
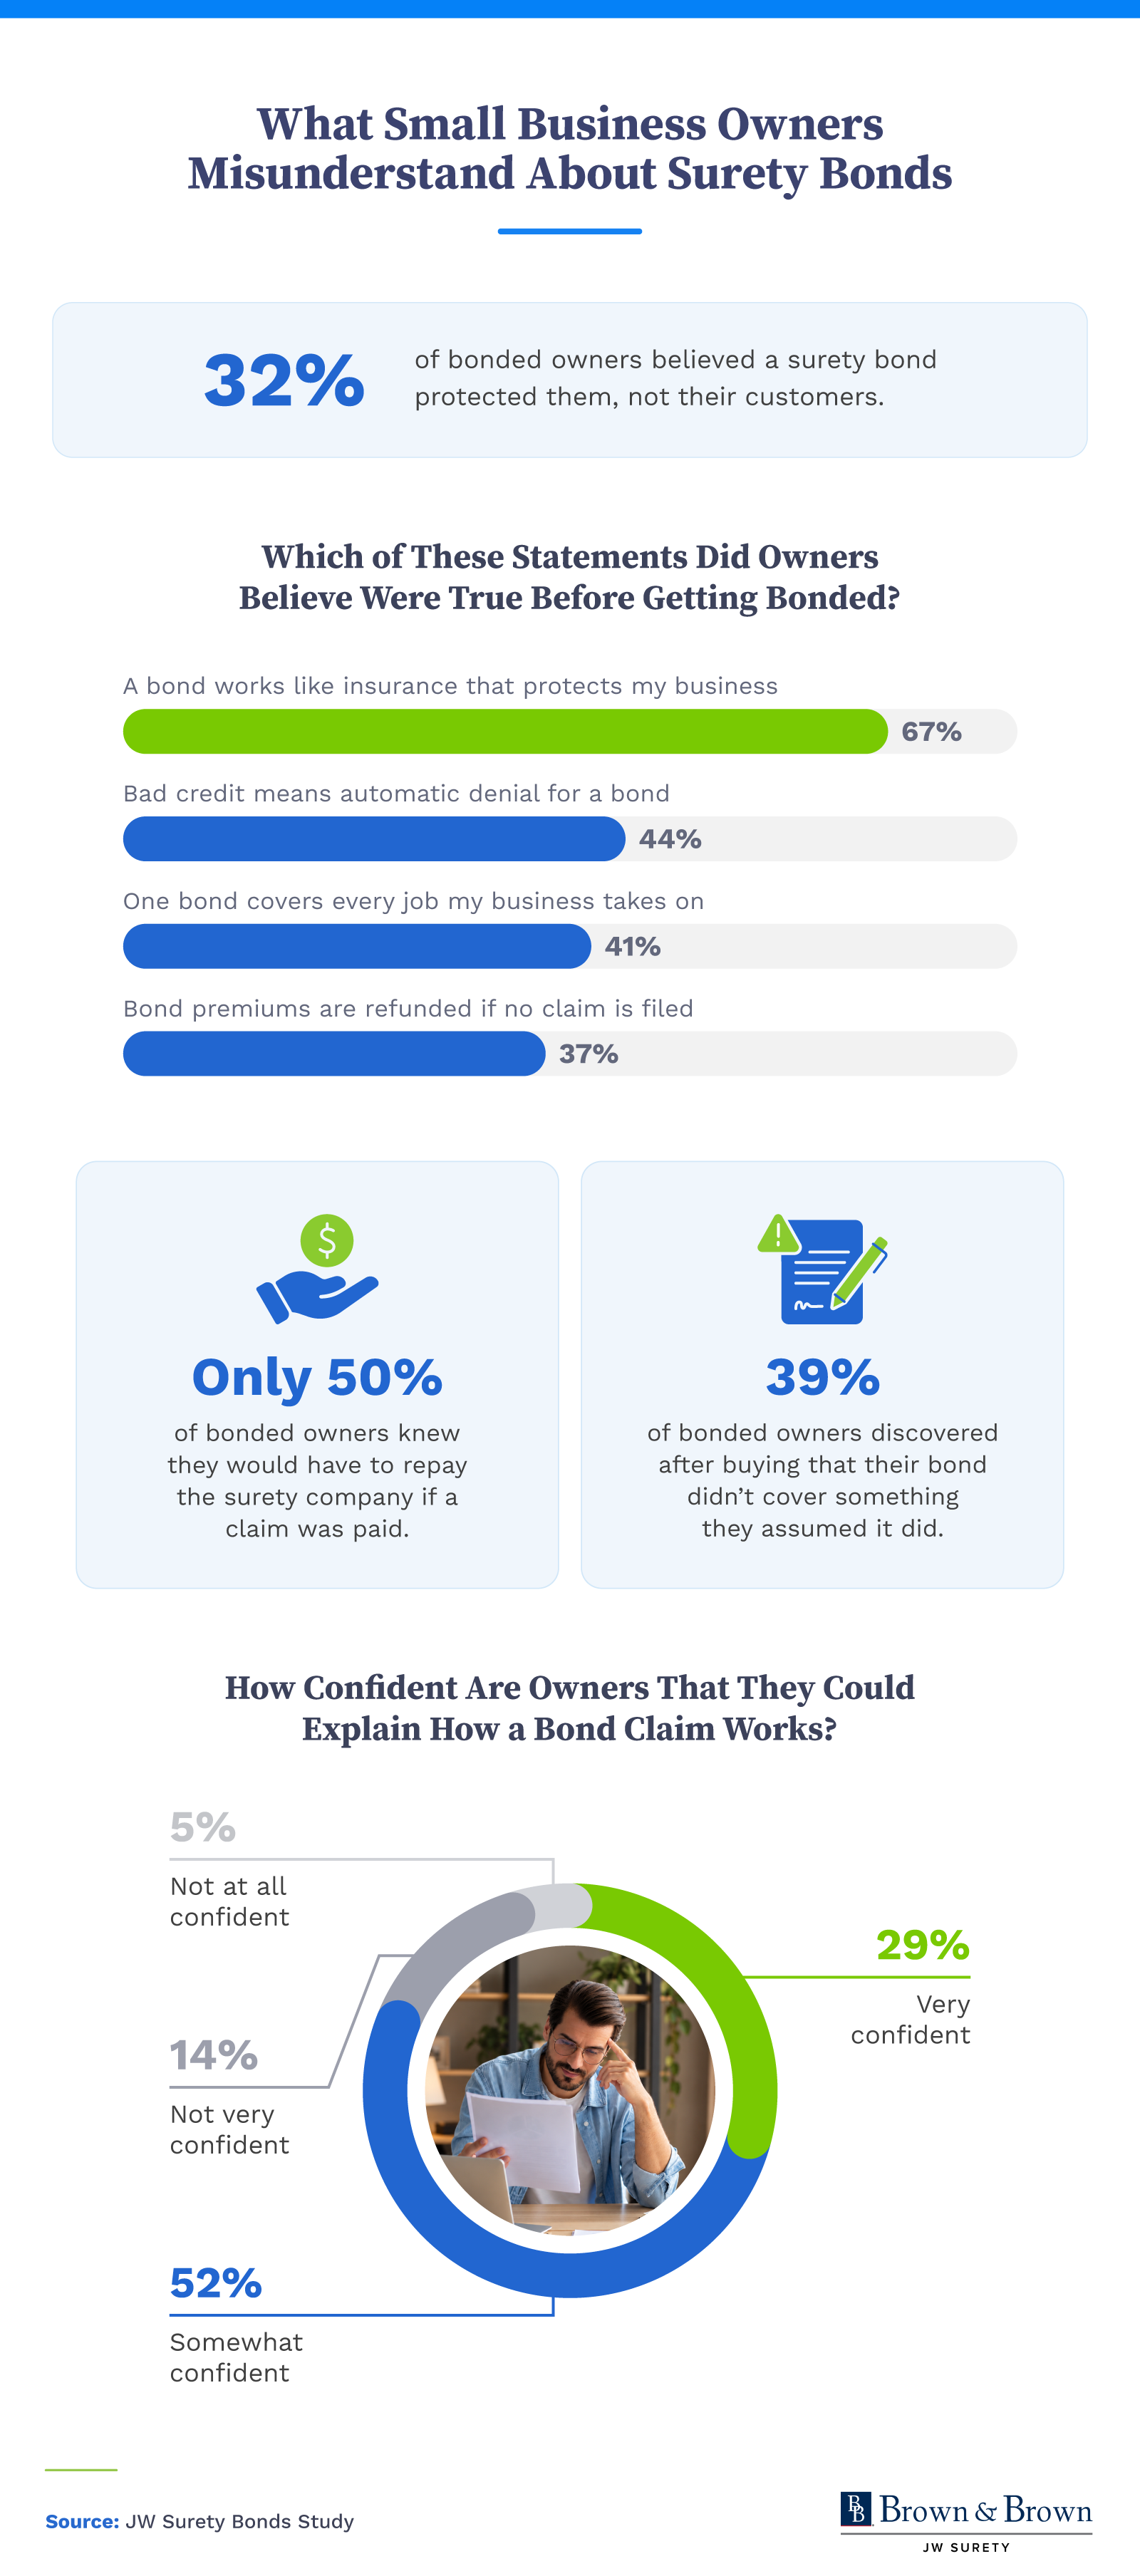
Most bonded owners felt knowledgeable about the claims process, with 81% expressing confidence in their ability to explain how a bond claim works. Yet that confidence didn't always align with their understanding of financial responsibility. Only 50% knew they would have to repay the surety company if it paid a claim.
Misconceptions about coverage were also common. Nearly 2 in 5 bonded owners (39%) discovered after purchasing their bond that it didn't cover something they had assumed it would. Another 32% mistakenly believed their surety bond protected them rather than their customers.
Unlike traditional business insurance, a surety bond generally protects the party requiring the bond, or those covered by its terms, if the bonded business fails to meet specific obligations. If a valid claim results in the surety company making a payment, the business is typically responsible for reimbursing that amount. Knowing these distinctions before buying can help owners better understand their responsibilities and avoid costly misunderstandings.
Where Business Owners Turn for Bond Guidance
Finding reliable information is an important part of navigating bonding requirements. With online resources and AI-powered tools readily available, business owners have several ways to research the process before making a purchase.
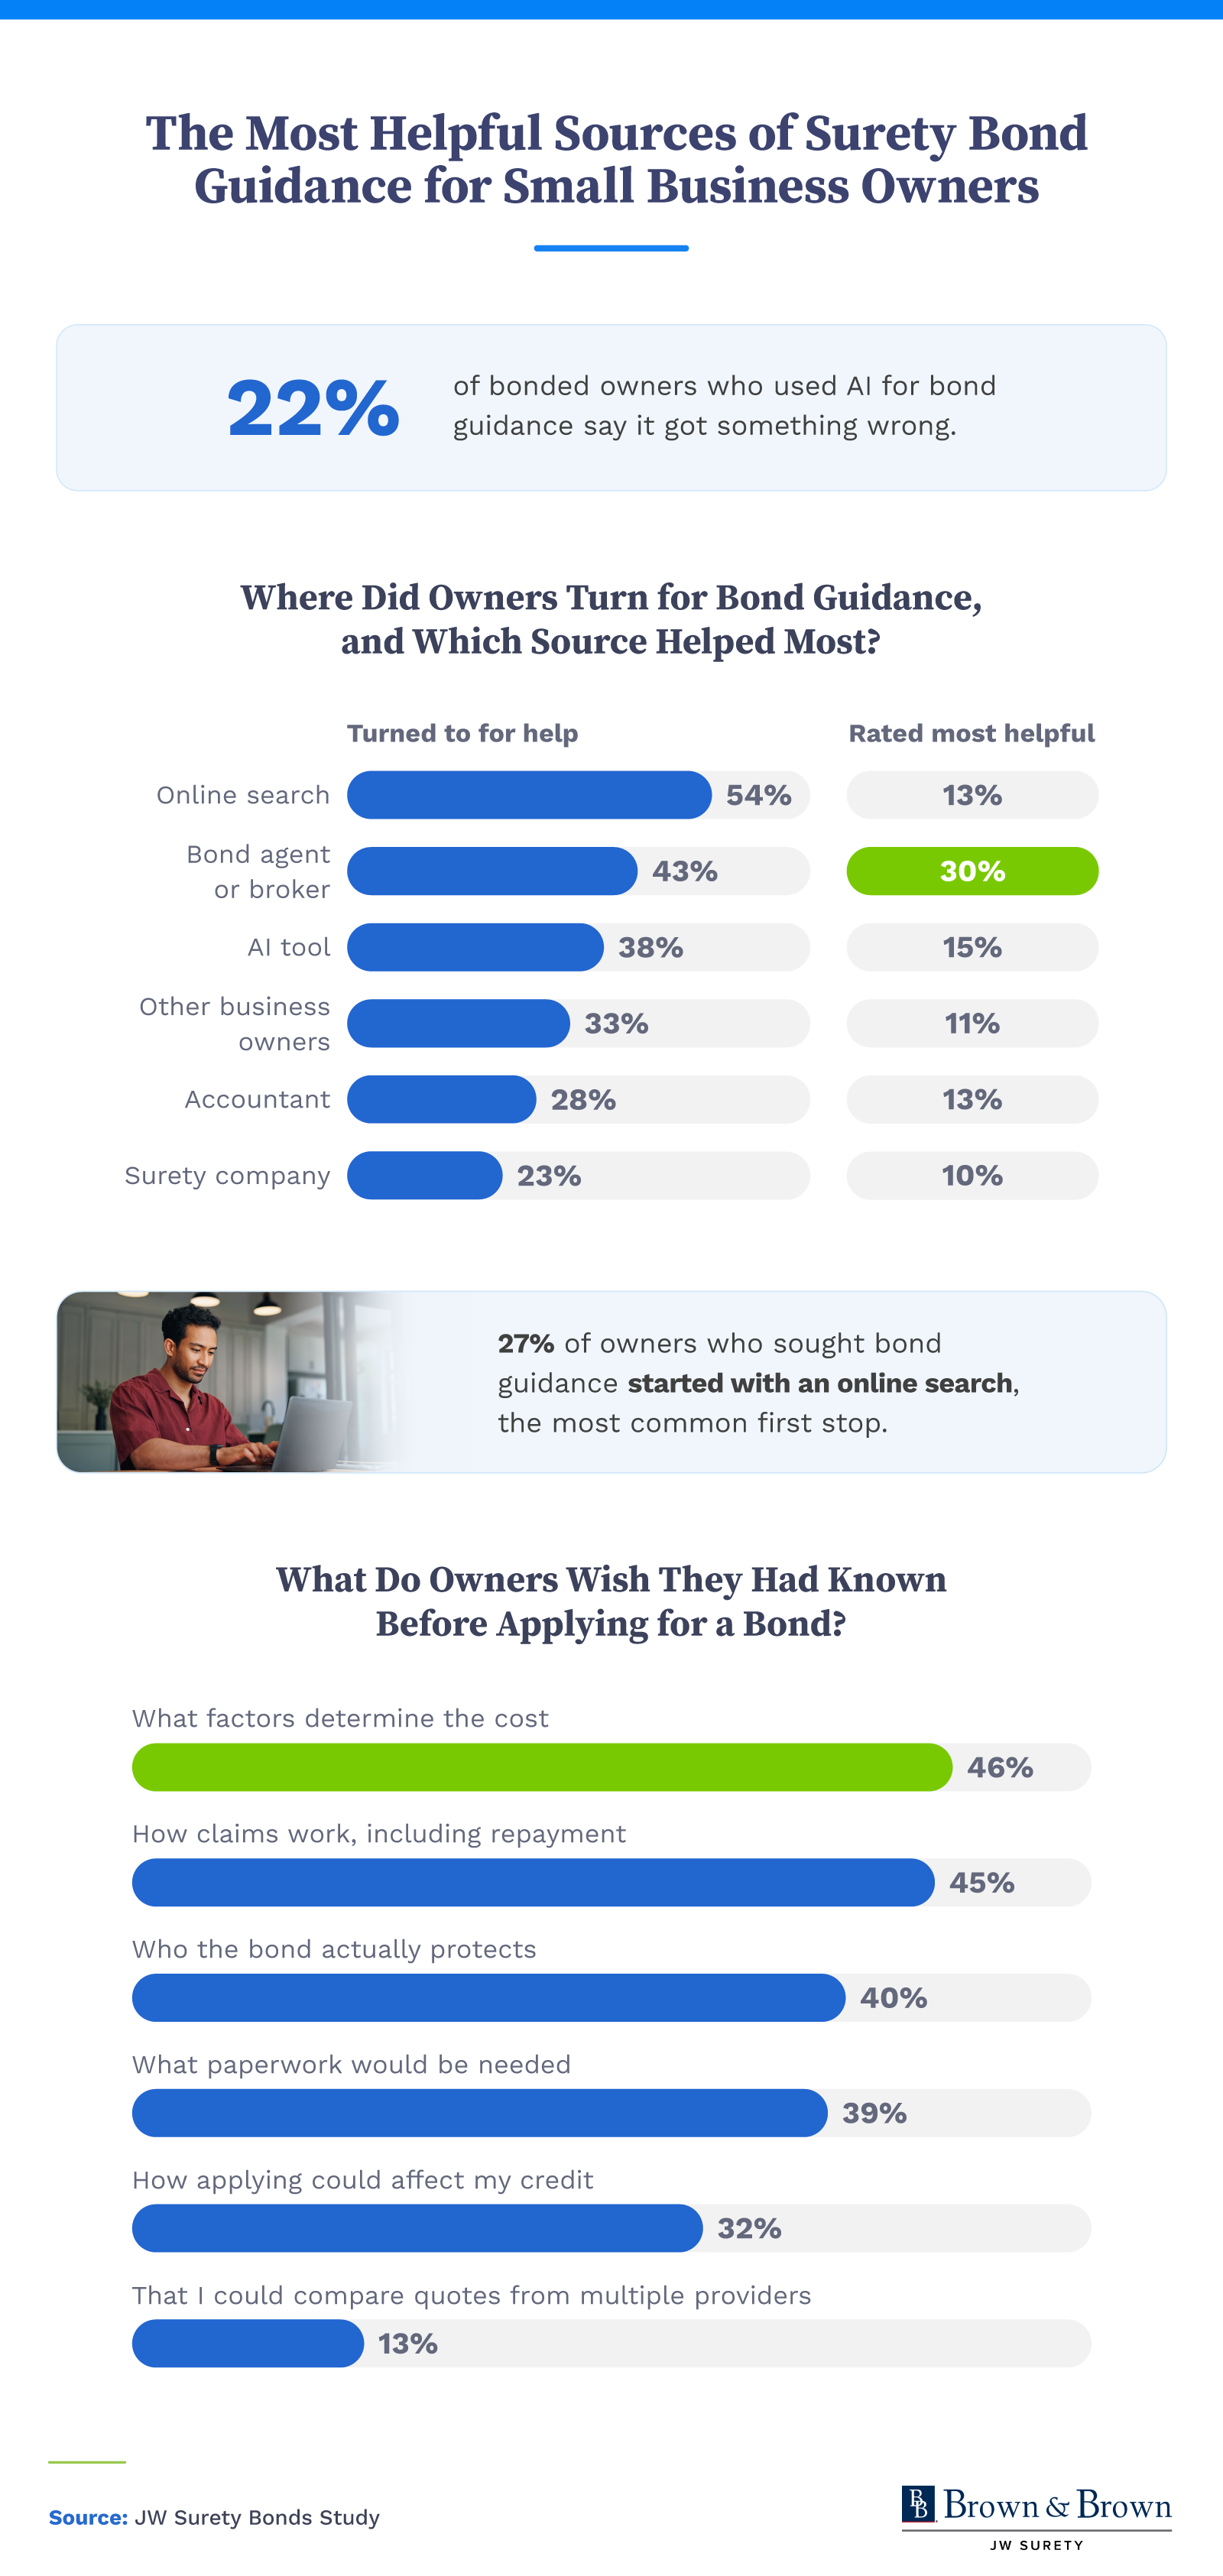
Online searches were the most common starting point for owners who sought bonding guidance, with 27% turning to a search engine first. This reflected the role digital resources played in helping business owners understand bond requirements and explore their options.
AI tools were another source of guidance, used by 38% of bonded owners. However, 22% of those who relied on AI reported receiving incorrect information. That experience raised concerns about relying on automated answers for details that could affect licensing, costs, or compliance.
While online searches and AI tools can help business owners become familiar with bonding terminology, it's important to verify specific requirements with the appropriate licensing authority or an experienced surety bond provider. Confirming the bond type, amount, and obligations before purchasing can help owners make more informed decisions.
Getting Bonded With Greater Confidence
For many small business owners, the biggest challenges of getting bonded weren't limited to completing paperwork. Unexpected costs, misunderstandings about coverage, and unreliable guidance affected their approach to business launches, contracts, and financial responsibilities.
The findings point to the value of preparing early, comparing options, and understanding what a surety bond does before committing to a purchase. Business owners who take time to verify requirements and ask questions can approach the process with greater clarity. When getting bonded is a requirement for moving your business forward, knowing what to expect can make all the difference between a missed opportunity and a confident next step.
Methodology
We surveyed 270 U.S. small business owners who purchased a surety bond in the past three years about their experience getting bonded, including costs and paperwork, claims, and who a bond protects. Respondents were 65% one-time bond buyers and 35% repeat buyers. They first got bonded to open a business (56%), meet a license or permit requirement (33%), or win or fulfill a contract (11%). The generational breakdown was 52% millennials, 24% Gen Z, 20% Gen X, and 2% baby boomers; 53% were women, 47% men, and 1% nonbinary. The margin of error is plus or minus 6 percentage points at a 95% confidence level. Data was collected in October 2026.
About JW Surety Bonds
JW Surety Bonds helps small business owners and licensed professionals navigate the bonding process with straightforward guidance and access to a wide range of surety bond solutions. Whether you're securing your first bond for a business license or meeting contract requirements, our experienced team can help you understand your options, compare costs, and get bonded with confidence.
Fair Use Statement
The findings in this article may be shared for noncommercial purposes only. Please provide proper attribution and a link to JW Surety Bonds when referencing or sharing this information.
Leave a Reply